If it were really free, why would the store offer it?
Every festive sale season, "No-Cost EMI" banners show up next to phones, laptops, and appliances, promising you can pay in instalments with zero extra interest. It sounds like a straightforward win: same price, more time to pay. But stores and lenders do not hand out free credit as a matter of goodwill — the cost is still there, it has just moved somewhere you are not looking.
This is not a claim that no-cost EMI is a scam. Often it genuinely is a fair deal, sometimes even a good one. The point of this article is to show you exactly where the "cost" in a supposedly costless EMI actually hides, so you can tell a good no-cost EMI offer from a mediocre one instead of assuming the label means the same thing every time.
Where the interest actually goes
In a normal EMI, the bank lends you money and charges interest on top, so your total instalments add up to more than the item's price. In a "no-cost" EMI, the lender still calculates interest the same way internally — it just gets subtracted from the item's price upfront (as a "discount") instead of being added to your instalments. Your EMI total ends up matching the sticker price, which is why it looks interest-free.
The catch is who pays for that discount. Usually the seller funds it, effectively splitting the item's margin with the bank to make the sale happen — and that cost is baked into the price for everyone, EMI or not. So the "discount" you would have gotten by paying cash upfront often disappears when you choose EMI instead, even though the EMI itself shows ₹0 extra interest.
On top of that, most no-cost EMI plans still charge a processing fee — commonly ₹99 to ₹999 depending on the lender and item value — plus 18% GST on that fee. That fee is real money out of your pocket, and it is where a meaningful chunk of the "hidden cost" actually sits.
GST on the interest component: the detail almost nobody notices
Here is a subtlety that catches a lot of people off guard: even though your EMI amount looks interest-free, GST authorities still treat part of the underlying transaction as containing an interest component, because that is what it economically is. Depending on how the specific lender and merchant structure the offer, this can show up as GST charged on the processing fee, or occasionally as a small additional charge folded into the total. It is rarely a large amount, but "no-cost" starts looking a little less than 100% no-cost once you add it up.
The honest way to know whether a specific offer is actually a good deal is not to trust the label, but to compare it against your real alternative: paying the full amount today and investing the difference, or paying cash and asking for the upfront discount you would get outside the EMI scheme.
The real comparison: EMI vs paying cash and investing the rest
Say a laptop costs ₹60,000, and the store offers "no-cost EMI" over 12 months — ₹5,000/month, no listed interest — plus a ₹199 processing fee. If you paid cash instead, imagine you could get a 3% instant discount, bringing the price to ₹58,200, and you could invest the ₹5,000/month you would have spent on EMI instalments into a fund earning a modest 6% annualised return over that year, since it is short-term money you might need soon.
The present value of paying ₹5,000 a month for 12 months, discounted back at that 6% rate, works out to roughly ₹58,100 — meaning the no-cost EMI is not "free" so much as roughly on par with the cash price after the discount, once you account for what your money could have earned elsewhere in the meantime. Add the processing fee and GST, and cash starts to edge ahead. This is a real, illustrative example — your own numbers depend on the actual discount offered, the fee charged, and what return you'd realistically earn on money you would keep uninvested for a year.
This is exactly the trade-off finkit's No-Cost EMI vs Upfront calculator and Loan vs Full Payment calculator are built to check: they take the item price, the EMI plan, any processing fee, and your expected alternative return, and tell you which path actually leaves you better off in present-value terms — not just which one has a lower sticker number.
When no-cost EMI is genuinely worth taking
None of this means you should always pay cash. No-cost EMI can be a perfectly sound choice when: you would not get a meaningful cash discount anyway, you would rather keep your cash liquid for an emergency fund or a better investment opportunity, or the processing fee is small relative to the purchase (a fee of ₹199 on a ₹1,50,000 purchase is basically negligible).
It stops being a good idea when the processing fee is disproportionately high for a small purchase, when a real cash discount was on the table and you skipped it without checking, or when you would have to withdraw from an investment earning far more than 6-8% just to free up cash for EMIs you did not need to take in the first place.
The fix is simple: before saying yes to a no-cost EMI banner, run the actual numbers instead of trusting the word "free". A five-minute check with finkit's calculators — entirely in your browser, nothing saved or sent anywhere — tells you whether this particular offer is a genuine convenience or a quiet markup wearing a friendly label.
The Flat Rate Trap: Why "10% Flat" Can Mean 18%+ in Reality
Car dealers and personal loan agents love quoting flat rates because the number sounds small. Here is the real interest rate hiding behind it.
5 min read
Lean, Coast, or Regular FIRE: Which One Actually Fits You?
FIRE is not one number or one strategy. Here is how the three common variants differ, and which finkit calculator matches each one.
5 min read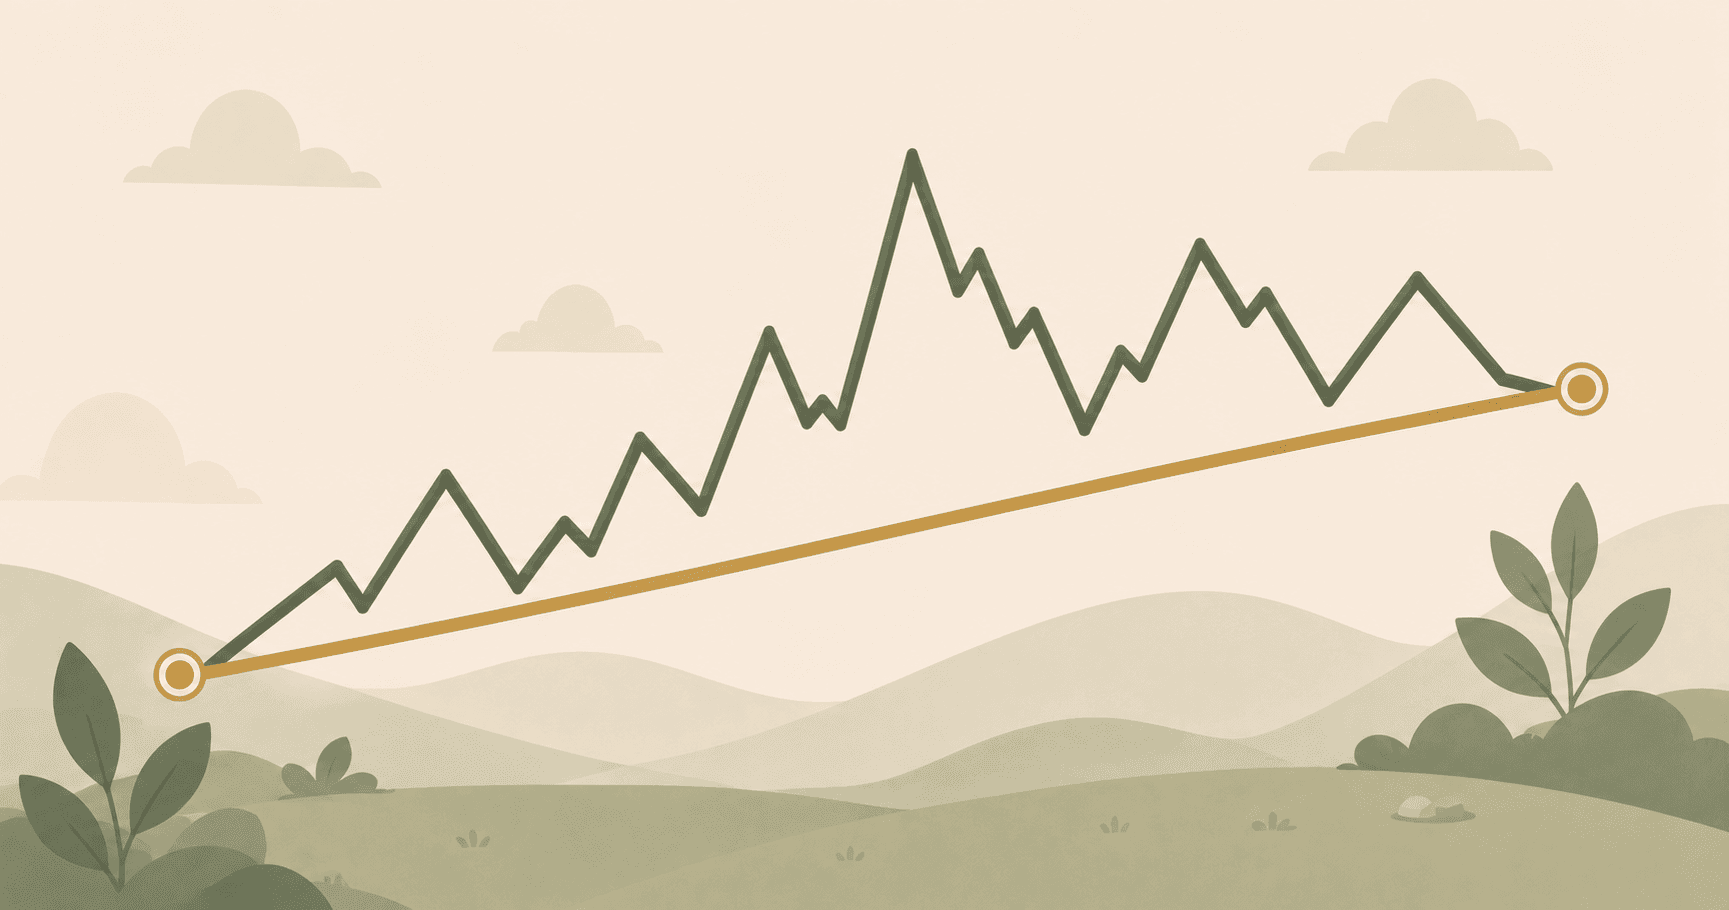
CAGR vs Average Returns: Why Your Fund's '15% Average' Isn't Real
A fund that rose 50% one year and fell 33% the next did not average 8.5%. It made 0%. Here is why CAGR tells the truth and simple averages do not.
4 min read