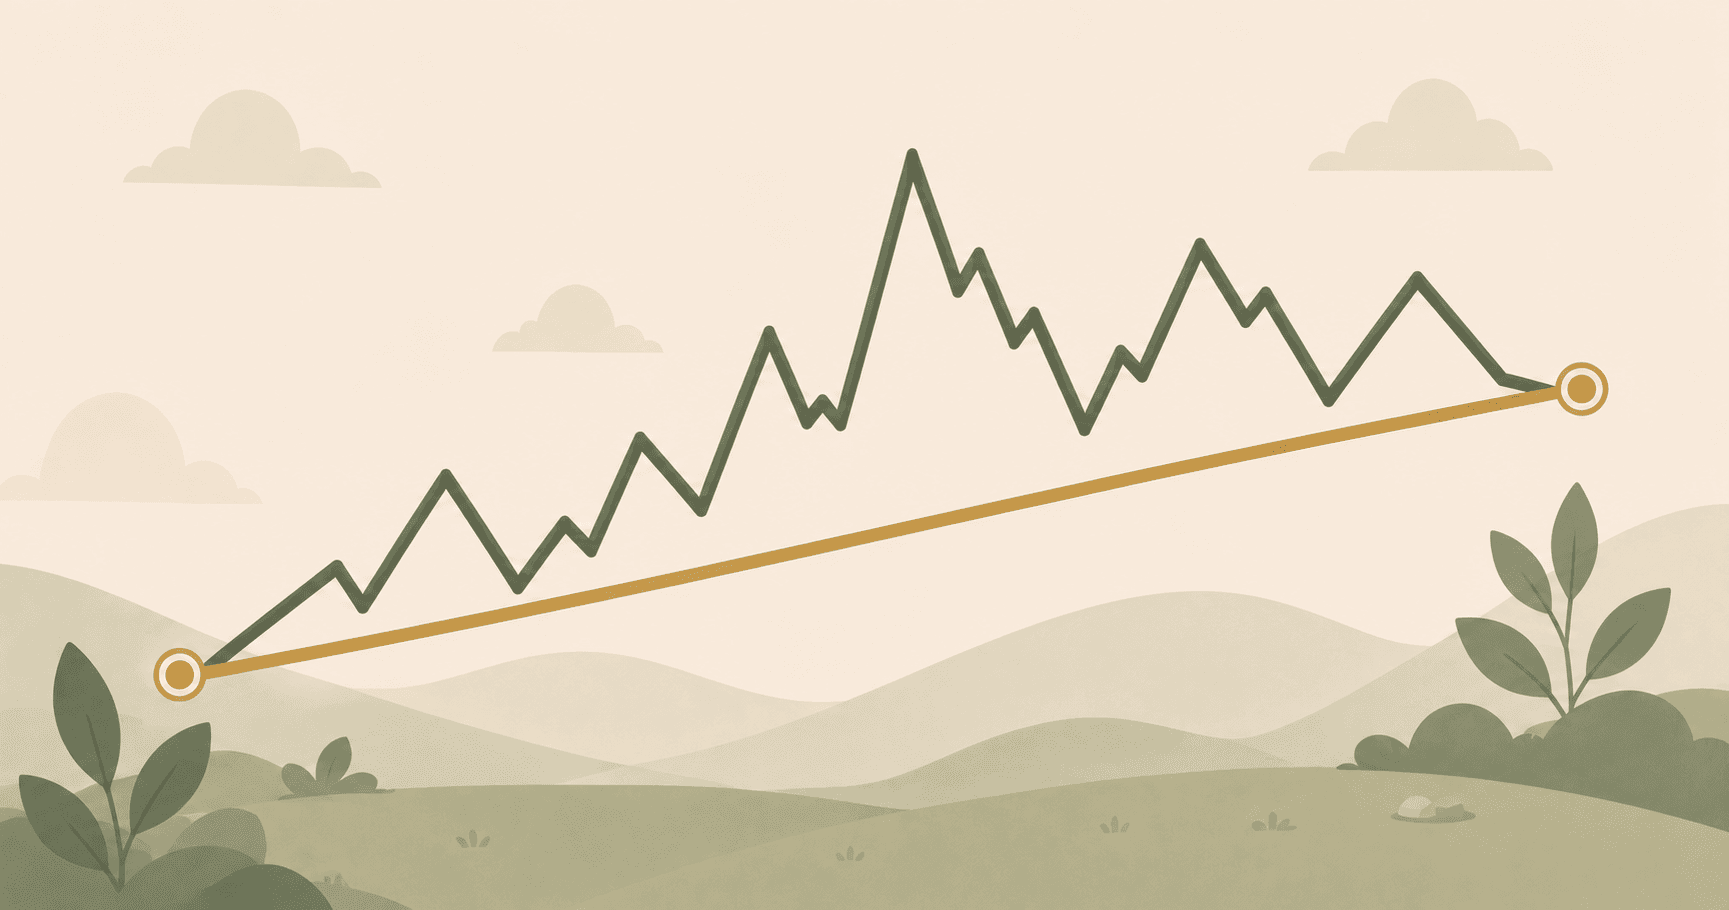
A number that looks right but is quietly wrong
Fund factsheets and advisor pitches love quoting an "average annual return" — add up each year's return and divide by the number of years. It feels intuitive, and it is also, for anything that compounds, mathematically misleading. The more volatile the returns, the bigger the gap between what that average implies and what your money actually did.
This matters because investment returns compound, and compounding is multiplicative, not additive. A simple average treats a 50% gain and a 33% loss as if they cancel out to a healthy positive number. They do not.
The example that breaks the intuition
Say a fund is worth ₹100 at the start. Year one, it rises 50%, taking it to ₹150. Year two, it falls 33.3%, taking it back down to ₹100. Your money is exactly where it started — a 0% return over two years.
But the simple average of the two yearly returns is (50% + (−33.3%)) ÷ 2 = about 8.3%. If someone tells you this fund "averaged 8.3% a year", it sounds like a solid, respectable return. In reality, you made nothing. The simple average is not lying about the individual years, but it completely misrepresents what happened to your actual money.
CAGR: the rate that actually matches your money
CAGR — Compound Annual Growth Rate — answers a different, more honest question: what single, constant yearly rate, applied every year and compounded, would take your starting value to your ending value over the actual period? In the example above, CAGR is exactly 0%, because that is what actually happened: ₹100 became ₹100.
The formula is CAGR = (Ending Value ÷ Starting Value)^(1 ÷ Years) − 1. It only needs two numbers — where you started and where you ended — plus the number of years in between. It deliberately ignores the bumpy path in the middle, which is both its strength (it tells you the real net outcome) and its limitation (it hides how rough the ride actually was).
This is exactly why CAGR, not a simple average, is the number worth asking a mutual fund or stock's actual multi-year performance for. When a factsheet advertises an eye-catching "average return", check whether it is really CAGR, and if it isn't, be skeptical — the gap tends to grow with how volatile the investment has been.
The gap gets worse the more volatile the ride
The 50%-then-−33% example is not an extreme cherry-picked case — sharp swings like that show up regularly in individual stocks, small-cap funds, and crypto. The more a fund's year-to-year returns swing up and down, the further its simple average drifts from its real CAGR, always in the optimistic direction. A fund that swings wildly but ends up flat will always show a positive-looking simple average and a 0% (or worse) CAGR.
A smoother, less volatile fund that returns a steady 10%, 11%, 9%, 10% each year has almost no gap between its simple average and its CAGR — because there is little compounding distortion to correct for. This is one more reason volatility is not just a risk metric on a chart; it directly eats into your realized long-term return in a way a simple average conveniently hides.
Check your own investments with the real number
If you know what an investment was worth when you started and what it is worth now, you can work out its true CAGR with finkit's CAGR calculator — just enter the starting value, ending value, and number of years, entirely in your browser. It is the same honest lens worth applying to your SIP or lumpsum projections too: finkit's SIP and Lumpsum calculators use consistent compounding math throughout, so the return rate you enter and the corpus you see out the other end tell a story that actually matches how compounding works, not a story flattened by simple averaging.
Step-Up SIP: The Small Yearly Increase That Roughly Doubles Your Corpus
Raising your SIP by 10% a year — matching a typical salary hike — can nearly double what a flat SIP builds over 20 years. Here is the actual math.
4 min read
Where Did My Money Go? The Question Every Tracker Fails to Answer
Why juggling a bank app, a card app, and a mental spreadsheet leaves you guessing — and what a finance dashboard built for how Indian money actually moves looks like.
4 min read
The Magic of Compounding: Why Starting Early Beats Investing More
A ten-year head start can beat decades of higher monthly investing — here is the math that proves why time wins.
5 min read