The three-app problem
Ask most people what they spent last month and they'll give you a shrug, not a number. Not because they don't care — because the answer is scattered across a bank statement, a credit card app, and maybe a mental note that gets forgotten by the 15th. Reconciling all three by hand, every month, is the kind of chore that nobody actually does, so most people just don't.
The usual fix — a budgeting app — often makes this worse before it makes it better. Log every ₹40 chai the moment you buy it, or the numbers drift. Pay for a subscription just to see your own spending. Hand your transaction history to a server you've never heard of. The app gets used enthusiastically for a week, then quietly abandoned, and the original question — where did my money go? — goes right back to being a shrug.
What actually needs tracking, and why it's harder than it looks
Indian money habits have a few specific wrinkles that a generic tracker usually gets wrong. A credit card's due amount isn't the same as its running balance — it's whatever the last closed statement adds up to, on a cycle that resets every month. An EMI isn't one transaction, it's a purchase quietly split into months of identical instalments you're expected to remember are coming. A home or car loan amortizes in the background for years, its outstanding balance shrinking on a curve nobody manually recalculates.
Get any of these wrong and the numbers just look off — a due amount that doesn't match the statement, a "balance" that ignores an EMI that hasn't landed yet. Get them right, and a dashboard can finally answer the question people actually ask: not "what's my balance," but "what do I still owe, and when."
What Finflow does with that
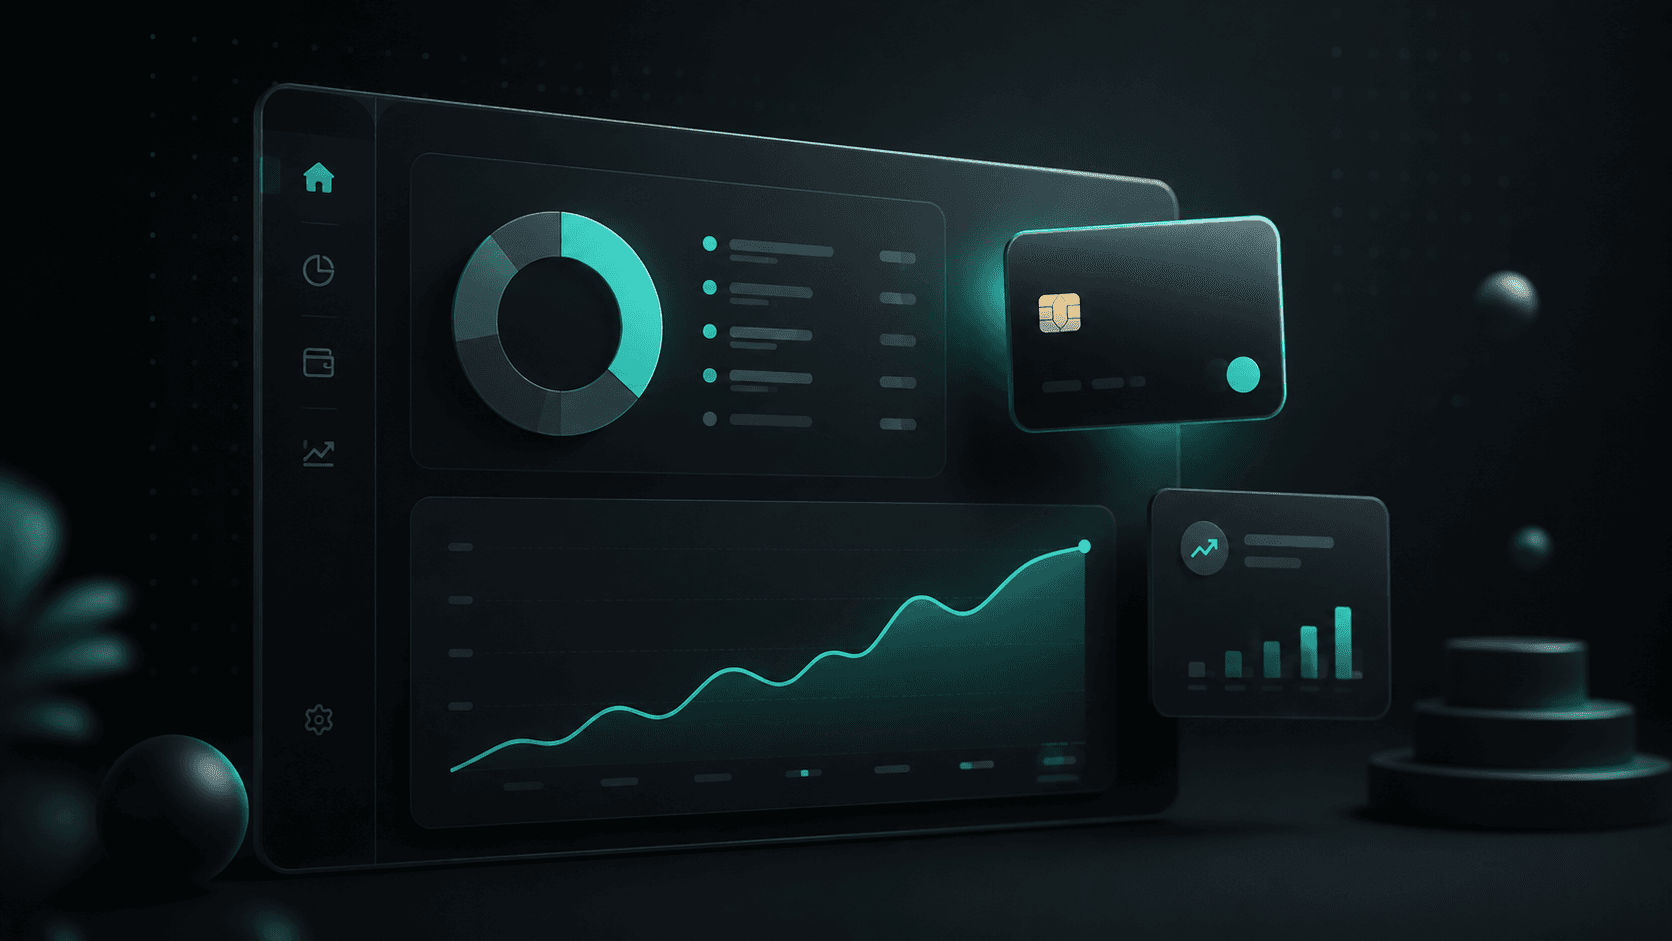
Finflow is a personal finance tracker built around that distinction. Every account — cash, bank, credit card, loan — feeds one dashboard: a spending breakdown by category, savings progress, net worth, and a month-over-month comparison, so a jump in spending is visible instead of buried in a statement.
Credit cards get their own due-amount calculation, tied to each card's actual billing and due day, not just its live balance. Loans and EMI plans — a home loan, a car loan, a purchase converted to instalments on a card — sit in one list with the next due date and how many instalments are left on each, so nothing quietly slips past because it wasn't the thing you happened to check that week. Investments sit alongside everyday spending too, with what's maturing soon surfaced rather than filed away in a separate app.
None of it asks for a subscription, and none of it leaves the browser to reach an ad network — it's built to answer one question honestly, not to hold your data hostage while doing it.
Try it
If you've ever opened three apps just to answer "can I afford this?", that's the exact question Finflow is for.
The Magic of Compounding: Why Starting Early Beats Investing More
A ten-year head start can beat decades of higher monthly investing — here is the math that proves why time wins.
5 min read
SIP vs Lumpsum: Which Wins When the Market Is Uncertain?
A plain-language look at investing a fixed amount every month versus investing it all at once, and when each makes sense.
5 min read
Emergency Fund 101: How Much Is Really Enough
What an emergency fund actually does for you, how to size one for your life, and simple steps to build it.
5 min read